When Portfolio Customisation Stops Being Private Banking
Direct indexing is bringing tax-aware, personalised portfolios to smaller accounts. Private banks will need to earn their premium elsewhere.
Private banks have long used portfolio customisation to justify part of their premium. Wealthy clients received individually managed securities, tax-aware transactions, investment restrictions and portfolios shaped around concentrated positions or personal preferences. Technology has started to strip away the scarcity behind that offer.
Direct indexing gives investors ownership of the individual securities inside an index rather than units in an index fund. Owning the underlying shares opens more opportunities to harvest losses stock by stock, exclude individual companies or change the weight of selected sectors and securities. Kiplinger’s October 2026 broker review already places direct indexing alongside robo advice, hybrid services and dedicated advisers rather than treating it as a specialist UHNW product.
Direct indexing itself is not new but software has changed the economics. Platforms monitor hundreds of positions, compare portfolios with their benchmarks, identify tax losses and process trades without requiring a portfolio manager to rebuild each account manually. Automation lowers the cost of running separate portfolios and lets providers offer customisation at account sizes that once made little commercial sense.
Private banks therefore face more than cheaper competition. One element of their traditional service is becoming standard investment infrastructure.
Tax Management Is Becoming a Feature
Tax-loss harvesting illustrates the pressure clearly. An investor holding an index fund owns one security. Direct indexing breaks the benchmark into individual holdings, creating more positions where losses can offset gains elsewhere while the portfolio retains similar market exposure. Kiplinger identifies tax-loss harvesting as one of direct indexing’s advantages.
Private banks still deal with tax problems that extend well beyond an equity account, especially where several jurisdictions, companies or ownership structures are involved. Software nevertheless handles much of the mechanical work inside listed portfolios. Banks have less room to charge a premium merely for describing a securities portfolio as tax-aware.
Personalisation faces similar pressure. A client may exclude tobacco, reduce technology exposure, introduce a value tilt or cap an individual stock. A portfolio manager once had to build and maintain many such variations by hand. Software turns a growing share of those instructions into portfolio rules.
A personalised portfolio therefore remains personalised, but fewer clients need a private bank to obtain one.
Lower Account Minimums Change the Comparison
Kiplinger’s broker review describes advisory services ranging from fully automated portfolios through hybrid models to dedicated advisers. Fidelity, for example, offers team-managed advice from $50’000 and access to a dedicated adviser for selected strategies from $100’000, while other providers set higher thresholds.
A US brokerage relationship does not offer the same service as a Swiss private bank. The comparison still changes client expectations. Investors with relatively modest portfolios now have access to automated portfolio construction, tax tools, digital reporting and human advice from one provider.
A private bank charging materially more has to account for the difference. Better implementation of listed securities no longer explains the whole premium.
The Listed Portfolio Is Often the Simple Part
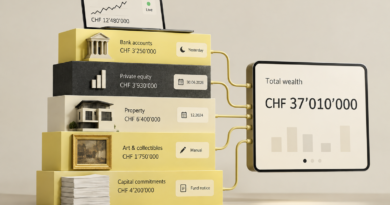
A wealthy family rarely owns only equities and bonds. A founder may hold a private company alongside several custody accounts, property, private-equity commitments and a listed portfolio. Another family may combine trusts, loans, direct investments, art and assets held across jurisdictions.
A direct-indexing engine works inside the securities account. It does not know that a private-equity fund will call CHF 2 million next quarter, that the family plans to refinance a property or that most of the family’s economic exposure still comes from one operating company.
Portfolio construction remains part of the work, but a private bank has more room to add value when it understands how every holding interacts with the rest of the balance sheet.
A tax loss harvested inside an equity account offers little help when poor liquidity planning forces the family to sell assets at the wrong time. A diversified securities portfolio does not solve concentration if most wealth remains tied to a private business. A low-volatility allocation may look appropriate until currency liabilities, property debt or future family distributions enter the calculation.
Private Banking Moves Beyond the Securities Account
A banker working with complex wealth needs to know where the money came from, which assets remain economically connected, where liquidity will be required and which decisions another generation will eventually inherit. Investment managers, lawyers, tax advisers and corporate advisers also need enough shared information to avoid solving one problem while creating another elsewhere.
Think of a client with CHF 40 million of total wealth. CHF 15 million sits in listed securities, CHF 10 million remains in a private company, CHF 7 million sits in property and CHF 8 million covers cash and private-market investments. Optimising the listed portfolio matters, but the client may have a more immediate decision: whether another CHF 3 million private-market commitment fits the family’s future liquidity needs.
Succession creates another layer as portfolio software can optimise securities for the current owner. It does not decide whether the next generation receives shares, cash, property or company ownership, nor how economic ownership and control differ between heirs.
Private banks retain a stronger role where investment decisions collide with ownership, liquidity, tax and family governance.
Bespoke Needs a New Definition
“Bespoke portfolio” once separated private wealth management from retail investing. Direct indexing and automated portfolio tools have narrowed the gap.
A modern bespoke service has to cover more than security selection. For a complex client, personalisation reaches into liquidity planning, private assets, financing, ownership structures, taxes and succession. Excluding five companies from an index and harvesting losses no longer carries enough scarcity to support a private-bank fee on its own.
Human judgement remains harder to automate when a family has several objectives and no single portfolio metric settles the decision. A founder deciding whether to sell part of a company, finance a child’s property purchase, increase private-market exposure and retain enough liquidity for future taxes faces linked choices across several asset pools.
Software will continue taking over repeatable portfolio work because scale rewards repeatable work. Private banks need to spend more time on the decisions that sit outside an individual account.
Where Private Banks Still Earn Their PremiumPortfolio construction: software and digital providers already handle much of the repeatable work.
Tax-loss harvesting: direct indexing has turned a specialist technique into a scalable portfolio feature.
Investment exclusions and tilts: platforms now implement many client preferences through portfolio rules.
Multi-bank consolidation: families with assets across several institutions still need one economic view of their wealth.
Private-asset liquidity planning: capital calls, distributions and uncertain exit dates require coordination across the wider balance sheet.
Concentrated wealth: founders need to manage the interaction between company ownership, listed investments and personal liquidity.
Succession and governance: software does not decide who receives control, ownership or liquidity.
Cross-border structures: investment decisions still depend on legal ownership, tax residence and jurisdiction.
What You Should Remember
Direct indexing removes another product-level advantage from private banks. The stronger private-banking proposition sits above the portfolio: understanding how securities, private assets, liabilities, tax, liquidity and succession fit together.