Your Heirs Do Not Need to Know the Number. They Need to Know the Structure
Inheritance planning works better when the next generation understands what the family owns, where assets sit and who controls them before any transfer takes place.
Families often delay inheritance conversations because they do not want to disclose a number too early. Parents worry about motivation, entitlement and privacy. Adult children often avoid asking because the conversation feels intrusive.
Kiplinger’s 2026 inheritance survey shows where silence leads. Morning Consult questioned 5’156 US parents and adult children. Some 42 percent of adult children said they did not expect a meaningful inheritance, while only 15 percent of parents said they expected to leave nothing. Children also underestimated how often their parents owned cash, property, insurance and investment accounts.
The mismatch goes beyond valuation. An heir may know that family wealth exists without knowing which bank holds it, whether property sits inside a company, who owns the voting shares in the family business or which private-market funds still have unfunded commitments. A family can keep the final value private and still answer those questions.
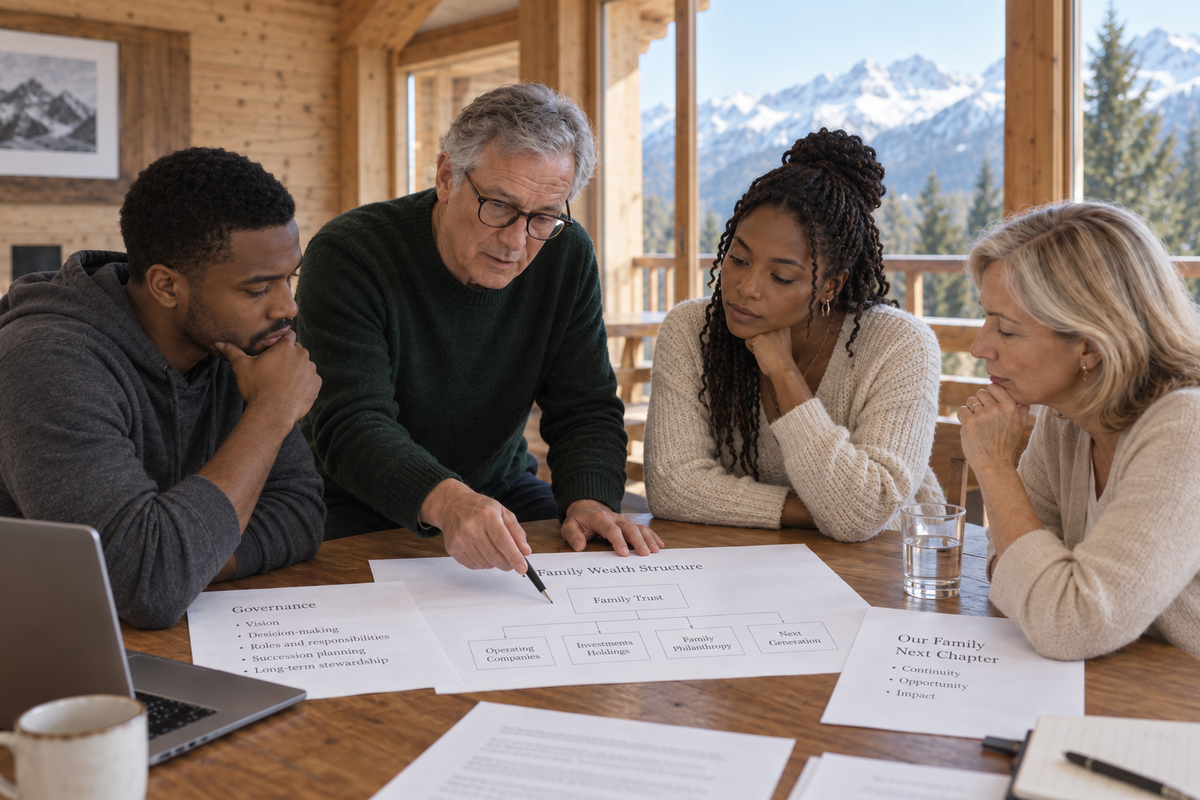
The transfer starts with an asset map
For a family with one house, one bank account and a securities portfolio, inheritance administration remains relatively visible. Wealthy families accumulate structures around the assets: holding companies, trusts, foundations, several banks, property vehicles, private-equity funds, insurance policies and operating businesses.
The current owner usually understands the history behind those arrangements. The next generation inherits the finished structure without necessarily knowing why it looks the way it does.
A founder may hold company shares personally while a separate entity owns the property used by the business. Investment assets sit across three banks because different relationships developed over time. A family office tracks private-equity commitments in another system. Legal documents live with an external lawyer.
Death or incapacity turns those arrangements into a set of immediate questions. Which entity owns which asset? Who has signing authority? Which bank relationship covers which portfolio? Where are the shareholder agreements? Which fund expects another capital call?
Kiplinger found that two in five families had never discussed inheritance plans and three in ten parents had no formal plan. A family office that already consolidates the information for the current generation has most of the raw material needed for succession. The harder decision concerns how much of it the family shares, and when.
Ownership and control rarely move together
An asset list does not explain who will make decisions. One child may inherit voting shares in a family company while another receives non-voting shares or liquid assets. A trust may distribute income while the trustee retains control over the underlying capital. Property may remain jointly owned even when family members disagree over whether to keep it.
Parents often focus on equal value and heirs live with the allocation of control. Kiplinger’s survey found a 21 percentage-point gap between younger and older respondents over whether inheritance should reflect factors such as financial need or previous support rather than follow a strictly equal split. The disagreement becomes harder to resolve when the first explanation arrives together with the inheritance itself.
A family does not need to negotiate every allocation with the next generation. It does need to explain the principle behind decisions that will affect siblings differently. A daughter who receives liquid investments and a son who receives a controlling company stake have not received the same type of asset even when an adviser assigns both holdings the same value. The company brings board decisions, employment questions and responsibility for other shareholders. The liquid portfolio does not.
A large estate may still leave a cash problem
Valuation often receives more attention than liquidity because the larger number looks more consequential. Private wealth does not always arrive in spendable form. A family may own an operating company, several properties, art and private-market funds while holding relatively little cash. Taxes, debt, legal costs and family distributions still arrive on schedule.
An heir looking only at headline wealth may assume liquidity exists where it does not. Private-equity commitments make the problem easy to see. A fund interest has a reported value, but the family may still owe future capital calls. Property adds another constraint: ownership transfers, but maintenance, financing and taxes continue. A private company may represent most of the estate while producing no near-term cash for family members who do not work in it.
A successor therefore needs more than a list of assets. The family office needs to identify which holdings generate cash, which require cash, which carry debt and which cannot be sold quickly without changing the family’s plans. The same information already matters while the founder is alive. Succession simply changes who needs access to it.
Advisers hold part of the family memory
A private banker knows the investment mandate. A tax adviser knows why one entity sits in one jurisdiction and another somewhere else. A lawyer knows the shareholder agreement. A trustee understands distribution rules that family members may never have read.
No single heir necessarily knows how those pieces connect. The problem becomes acute when one parent has handled nearly every financial relationship. Kiplinger found that 45 percent of fathers in its survey had said nothing to their children about inheritance plans, compared with 33 percent of mothers. A family whose financial knowledge sits largely with one person carries an operational dependency as well as a succession problem.
An adviser map belongs next to the asset map. Heirs need to know who does what, who holds which documents, who has authority to act and which relationships the family depends on.
Names alone are not enough. A lawyer who drafted a trust twenty years ago and has had no involvement since plays a different role from a lawyer who still advises the trustees. A bank holding a custody account differs from a bank providing credit against several family assets. Succession exposes those distinctions quickly.
Disclosure does not have to begin with valuation
Parents who fear disclosing too much often treat inheritance planning as a binary choice: tell the children everything or tell them nothing.
The information does not need to arrive in one meeting.
A younger family member may first learn where key documents sit and which entities exist. Later conversations can cover ownership, decision rights, debt and liquidity. Private-market commitments or company governance become more appropriate once the heir has enough context to understand them. Exact valuations can remain confidential until the family decides disclosure serves a practical purpose.
Kiplinger cites Fidelity’s description of wealth transfer as a process unfolding over decades rather than a single event at the reading of a will. Families already transfer responsibility gradually when they make gifts, bring children onto boards, introduce them to advisers or give them oversight of selected assets. The information architecture needs to develop alongside the responsibility.
What Your Heirs Need to Know Before They Know the Number
Where the assets sit
Banks, custodians, companies, trusts, foundations and other ownership vehicles.
Who owns and controls them
Share classes, trustees, directors, signatories and voting rights.
Which holdings require liquidity
Debt service, tax obligations, private-market capital calls and recurring family commitments.
Which assets are hard to sell
Private companies, property, private funds, art and other illiquid holdings.
Who holds the knowledge
Bankers, lawyers, tax advisers, trustees, accountants and family-office staff.
Where the documents are
Wills, shareholder agreements, trust deeds, insurance policies, mandates and access instructions.
Why the structure exists
The reasoning behind ownership, control and allocation across family members.
Heirs do not need the final valuation to prepare for an inheritance; they need a clear map of the assets, ownership, liquidity, advisers and decision rights they will eventually inherit.