The AI Boom Is Changing South Korea’s Wealth Map
Artificial intelligence has turned South Korea’s semiconductor industry into one of Asia’s most powerful engines of wealth creation. The gains extend well beyond Samsung and SK Hynix, but they are also leaving some of the country’s largest private fortunes more exposed to the same technology cycle.
South Korea’s Kospi rose 4.4% in a single session in July as investors responded to higher spending plans from US technology groups and stronger demand for Asian semiconductors. Alphabet’s investment plans helped reinforce expectations that the hyperscaler spending cycle still had room to run, a development fund managers saw as particularly supportive for the region’s chipmakers.
The rally also reflected a broader shift in South Korean wealth. Artificial intelligence has raised the value of memory chips, semiconductor equipment and the companies that make them, lifting technology fortunes while strengthening the position of families already at the centre of the country’s corporate system.
Forbes estimated the combined wealth of South Korea’s 50 richest people at US$175bn in April 2026, up 77% from US$99bn a year earlier. The Kospi had more than doubled over the period used for its annual comparison, while 34 of the 50 fortunes increased. Semiconductor demand was one of the main drivers.
The change is most visible at Samsung. Jay Y. Lee, executive chairman of Samsung Electronics, returned to the top of South Korea’s wealth ranking with an estimated fortune of US$21.6bn in April. By May, after another sharp rise in Samsung shares, Forbes put his real-time wealth at US$34bn. His mother, Hong Ra-hee, and sisters Lee Boo-jin and Lee Seo-hyun occupied the next three positions, making four members of the same family South Korea’s four richest people at that point.
Such concentration reflects the way South Korean wealth remains tied to corporate ownership. Much of the Lee family fortune depends on Samsung-related shareholdings, so a re-rating of the group’s most important listed company can alter family wealth on a scale rarely seen in more diversified portfolios. AI has sharpened that effect by moving memory closer to the centre of the technology investment cycle.
Memory has become AI infrastructure
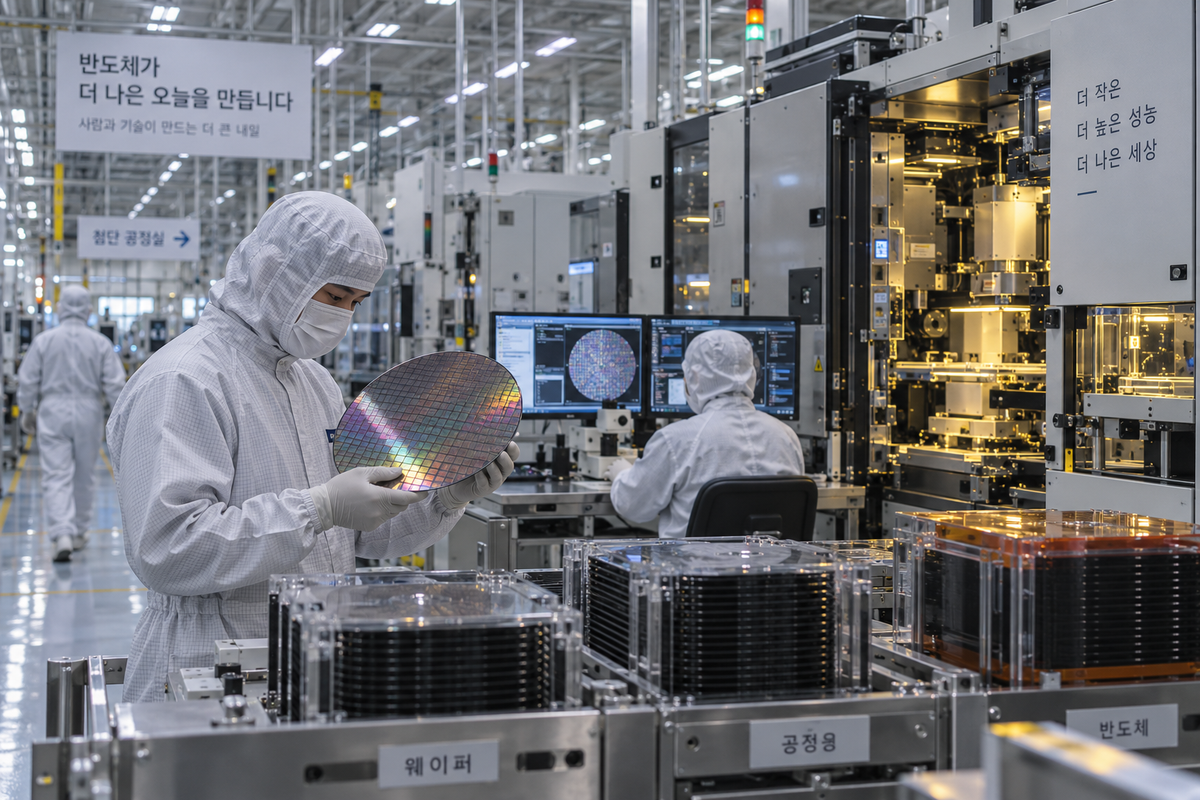
Generative AI requires processors that can move vast quantities of data quickly, increasing demand for high-bandwidth memory, or HBM. These chips sit alongside graphics processors and other AI accelerators, helping them handle increasingly demanding computing workloads.
South Korea is unusually well placed to benefit. Samsung Electronics and SK Hynix are two of the world’s largest memory manufacturers, supported by a dense network of Korean equipment and component suppliers.
SK Hynix established an early lead in advanced HBM, while Samsung has been trying to recover ground. In February, Samsung said it had begun shipping HBM4 products to customers. The company said the chips could sustain speeds of 11.7 gigabits per second, 22% above its HBM3E generation, while SK Hynix was already producing HBM4 at scale.
The spending cycle has continued to support both groups. Handelsblatt reported in July that stronger cloud growth was encouraging higher AI investment and reinforcing expectations that hyperscaler spending had not yet peaked, providing one of the strongest tailwinds for Asian chipmakers.
By October, Samsung forecast third-quarter operating profit of KRW 107.4tn, compared with KRW 12.1tn a year earlier, as AI infrastructure demand and a global memory shortage lifted prices for HBM as well as conventional DRAM and NAND products. The financial effects now reach far beyond the companies selling the main AI processors.
New fortunes are appearing further down the supply chain
South Korea’s wealth gains are no longer confined to the families behind its largest conglomerates. Kwak Dong-shin, chairman and chief executive of Hanmi Semiconductor, increased his estimated fortune more than fourfold to US$5.7bn in Forbes’ April ranking. Hanmi makes equipment used in semiconductor production and has benefited from the expansion of advanced memory capacity.
The same ranking added billionaires from less visible parts of the AI supply chain. Sung Kyu-dong, founder of semiconductor-equipment group EO Technics, entered the list, as did Kim Sang-beom, chairman of ISU Group. Its ISU Petasys subsidiary supplies printed circuit boards to companies including Nvidia and Microsoft.
The AI investment cycle is therefore broadening the sources of technology wealth in South Korea. Memory manufacturers remain dominant, but spending on new capacity is also flowing to equipment makers, materials specialists, circuit-board producers and other suppliers.
That gives South Korea a different wealth profile from markets where AI fortunes are concentrated mainly among software founders. The country’s advantage rests on manufacturing capacity built over decades, allowing industrial founders and families to benefit from AI spending without running AI companies themselves.
For wealth managers, these clients look very different from technology entrepreneurs who sell a business and receive cash. Much of their wealth remains locked in listed operating companies.
Rising wealth does not necessarily mean greater diversification
A strong semiconductor cycle can increase a family’s net worth rapidly while leaving its underlying exposure largely unchanged. The Lee family provides the clearest example. Higher Samsung Electronics shares increase the value of family holdings but also raise the share of wealth tied to the same corporate ecosystem. Founders, executives and suppliers can face a similar problem when most of their personal assets consist of company stock.
A portfolio can therefore contain several investments while remaining exposed to the same economic driver. A founder may own shares in a semiconductor-equipment business, Korean equities, private technology holdings and property financed from the operating company. Legally, these are separate assets. Economically, several may depend on the same semiconductor cycle.
Rapidly rising company shares affect liquidity, tax planning and governance, while diversification can be difficult when selling stock appears to reduce exposure to the very business that created the fortune.
South Korea adds another complication through its inheritance-tax system. The OECD describes the country’s inheritance tax as one of the heaviest among member states, with rates ranging from 10% to 50% and the top rate applying to taxable estates above KRW 3bn. Inheritance and gift taxes generated around 2.4% of total tax revenue in 2024, the highest share in the OECD.
For families whose wealth consists largely of corporate shares, succession can therefore require substantial liquidity while preserving control remains a priority. The Lee family has already faced that tension. After the death of Samsung patriarch Lee Kun-hee in 2020, his heirs faced an inheritance-tax bill of roughly KRW 12tn. Higher valuations increase wealth, but they can also increase the cost of transferring it.
AI is reinforcing old wealth while creating new wealth
South Korea differs from markets where the AI boom has mainly created a new generation of technology founders. New fortunes are emerging among semiconductor-equipment and component manufacturers, yet AI is also increasing the value of businesses already controlled or heavily influenced by some of the country’s established industrial families.
SK provides another example. Chairman Chey Tae-won’s wealth is tied to a conglomerate spanning semiconductors, telecommunications, chemicals and energy, with SK Hynix now occupying one of the most valuable positions in the global AI supply chain. Forbes estimated Chey’s fortune at US$2.9bn in its April 2026 Korean rich list; its real-time estimate had risen to US$5.4bn by September.
The semiconductor cycle is therefore changing the value of Korean fortunes faster than the structures through which many of them are held. Samsung, SK Hynix and their suppliers benefit from a global build-out whose main customers often sit in the United States. Wealth may accumulate in South Korea, but its value increasingly depends on capital-spending decisions made by US hyperscalers, global demand for AI computing and a semiconductor supply chain stretching across Taiwan, China, Japan and America.
That leaves wealthy families with substantial upside, but also with a narrow set of common risks. South Korea’s AI boom is producing two changes at once. It is creating new fortunes among companies that were previously little known outside semiconductor manufacturing, while making several established industrial families substantially richer.
For family offices and advisers, the more important question is whether that wealth can be turned into durable family capital. Much of it remains concentrated in operating companies and their suppliers. Diversifying some of those gains without weakening control will determine whether the semiconductor boom merely lifts headline fortunes or changes South Korea’s private-wealth landscape more permanently.
ROTHARIA VIEW
AI wealth in South Korea remains unusually concentrated in listed industrial businesses.
For UHNWI individiduals benefiting from the semiconductor cycle, four exposures deserve particular attention:
Operating-company concentration
A rising share price can increase family wealth while leaving most capital dependent on one business.
Supply-chain correlation
Semiconductor shares, supplier holdings and private technology investments can all respond to the same AI capital-spending cycle.
Succession liquidity
Higher valuations can increase the value transferred between generations while substantial inheritance-tax liabilities create a need for cash.
Geographic diversification
Korean semiconductor wealth increasingly depends on global AI spending, making international assets an important counterweight to domestic operating exposure.