Private Equity Is Building an Exit Market of Its Own
Private equity has a liquidity problem. Funds are holding assets for longer, distributions have slowed and investors still need cash to meet new commitments or rebalance portfolios. Secondary markets have become one of the main ways the industry is dealing with it.
The scale has changed quickly. Jefferies estimates global secondary transaction volume reached a record $240 billion in 2025, up 48 percent from 2024. LP-led transactions accounted for $125 billion, while GP-led deals reached $115 billion. Five years earlier, GP-led secondaries were worth about $35 billion.
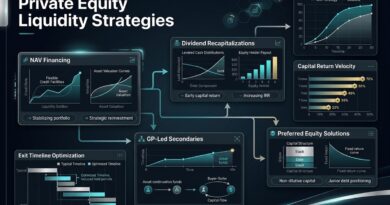
LP-led deals are the more familiar part of the market. An investor sells an existing fund interest to another buyer rather than waiting for the fund to wind down. That gives pension funds, endowments, family offices and other LPs a way to raise cash, reduce exposure to a manager or vintage, or make room for new commitments.
Pricing tells investors how much that liquidity costs. Jefferies puts average LP portfolio pricing at 87 percent of net asset value in 2025. Buyout portfolios averaged 92 percent of NAV, while venture and growth interests traded closer to 78 percent. Older funds generally sold at steeper discounts: portfolios more than ten years old averaged 73 percent of NAV.
The more important structural change is happening on the GP side. Managers increasingly use continuation vehicles to keep assets they do not want to sell outright. Existing investors are offered a choice: take liquidity or roll their stake into a new vehicle that holds the company for longer.
GP-led volume reached $115 billion in 2025, up 53 percent year on year, and continuation vehicles made up most of that activity. Jefferies estimates they already represent about 14 percent of sponsor-backed exit volume. Evercore separately reported $106 billion of GP-led transactions in 2025, with single-asset continuation vehicles accounting for $52 billion.
That changes what an “exit” means in private equity. A manager no longer has to choose only between selling a company, listing it or holding it inside the original fund. A continuation vehicle creates another route: return capital to investors who want out while keeping ownership of an asset the manager still believes has room to grow.
The structure also creates conflicts that investors need to examine closely. The same GP may effectively sit on both sides of the transaction, setting up the sale from the old fund and continuing to manage the asset in the new one. Valuation, transaction fees, carry resets and the quality of the price-setting process therefore matter as much as the underlying company.
Secondary buyers take the other side because they can enter assets later in their life cycle, often with more information than was available when the original fund invested. A portfolio might already contain mature companies, clearer exit paths and shorter remaining holding periods. The discount to NAV can improve the economics further, although it does not remove the underlying business or valuation risk.
Capital has followed the opportunity. Jefferies estimates dedicated secondary capital reached $327 billion in 2025 and around $477 billion when traditional LP capital and available leverage are included. Three of the ten largest private equity funds closed during the year were secondary-focused vehicles.
The market is also spreading beyond buyout funds. Private credit secondaries reached about $20 billion in 2025, almost double the previous year, while infrastructure and other real-asset secondaries are expanding as those markets mature.
For investors, the practical point is not simply that private equity has become more liquid. It has become more negotiable. Fund interests, mature portfolios and individual companies now have more routes to a new owner than they did a decade ago.
That flexibility comes with a price. Sellers may accept a discount, buyers have to judge whether reported NAVs are realistic, and continuation vehicles require close scrutiny of conflicts and incentives. But the old assumption that private equity capital remains locked up until the manager decides to exit is becoming less accurate.
Secondary markets are no longer a niche used mainly by investors under pressure. They are becoming part of the operating machinery of private equity: a market for freeing capital, extending ownership and putting a price on assets before the original fund reaches the end of its life.